
Saturday, September 26, 2026
Condo Financing Changes: What Chicago and Evanston Buyers Should Know
When buyers think about qualifying for a mortgage, they usually focus on their own finances: income, credit, down payment, debt, and interest rates.
With a condominium, however, the building itself can also affect financing. A financially qualified buyer may still encounter lending issues if the condominium association does not meet a lender's requirements.
Reserves, insurance, deferred maintenance, special assessments, litigation, and other association matters can all affect whether conventional financing is available for a particular unit.
Read full article here: https://www.willtveit.com/condo-financing-changes-chicago-evanston


Renting vs. Buying in Chicago | What Newcomers Should Know
Moving to Chicago often starts with one big question: Should I rent first, or buy right away?
There isn’t one right answer, but there are a few Chicago-specific factors that can make the decision easier.
Read full article here: https://www.willtveit.com/renting-vs-buying-in-chicago


What Is Your Home Really Worth? How to Price Your Home for Sale
The honest answer is that no online estimate, neighborhood average, or recent sale can determine your home's value on its own. A realistic price requires looking at the property, recent comparable sales, current competition, and what buyers are willing to pay now.
That is true whether you own a single-family home, condominium, townhome, or small multi-unit property in Evanston, Chicago, or the North Shore.
Online estimates can be a useful starting point, but they have not walked through your home. They may not know that you renovated the kitchen, replaced the roof, added a bathroom, or have a much better view than another unit in the same building. They may also miss condition issues that a buyer will notice immediately.
If you are wondering what your home is worth, the details matter.
Read full article here: https://www.willtveit.com/what-is-my-home-worth-evanston-chicago


Moving to Chicago for Work? A New Resident’s Relocation Checklist
Moving to Chicago for a new job can be exciting, but the practical details can pile up quickly. Beyond choosing the right neighborhood and home, new residents need to navigate transportation, vehicle requirements, utilities, parking, moving logistics, housing costs, and the everyday services that make a new city feel like home.
Whether you are relocating for Google’s new Chicago office at the Thompson Center, another downtown employer, or a position elsewhere in the Chicago area, this practical checklist can help you get organized.
Read full article here: https://www.willtveit.com/moving-to-chicago-relocation-checklist


What Is My Home Worth?
The honest answer is that no online estimate, neighborhood average, or recent sale can determine your home's value by itself. A realistic price requires looking at the property, recent comparable sales, current competition, and what buyers are willing to pay now.
That is true whether you own a single-family home, condominium, townhome or small multi-unit property in Evanston, Chicago or the North Shore.
Online estimates can be a useful starting point, but they have not walked through your home. They may not know that you renovated the kitchen, replaced the roof, added a bathroom, or that your unit has a much better view than another one in the building. They may also miss condition issues that a buyer will notice immediately.
If you are wondering what your home is worth, the details matter.
Read the full article here: https://www.willtveit.com/what-is-my-home-worth


Where Should You Live Near Google’s New Chicago Office?
Google’s move into its new Chicago office at the redeveloped Thompson Center is expected to bring roughly 2,000 employees into the heart of downtown Chicago, creating new interest in neighborhoods with convenient access to the Loop.
Google is expected to begin moving employees into the Thompson Center in 2027. The building sits at 100 W. Randolph Street and offers exceptional public transportation access, including six CTA ‘L’ lines serving Clark/Lake.
Are you relocating to Chicago to work at Google’s new Thompson Center office—or taking a position with another downtown employer? One of your first big decisions may be where to live.
But working downtown does not mean you have to live downtown.
With the Thompson Center in one of Chicago's most transit-connected locations, employees relocating to the city can realistically consider a wide range of neighborhoods based on budget, lifestyle, commute preferences, and the type of home they want.
Read full article here: https://www.willtveit.com/google-chicago-thompson-center-relocation


Meet Will Tveit: Evanston Realtor
I have spent much of my career helping people decide where and how they want to live. I have called downtown Evanston home for more than two decades, so I understand how much the right location affects everyday life.
My home, office, gym, favorite restaurants, the lakefront and two train lines are all within walking distance. That is one of the main reasons I still enjoy living here. Evanston offers neighborhood character, convenient access to Chicago and a lifestyle that does not require getting into a car every time I leave home.
Read full article here:. Ihttps://www.willtveit.com/meet-will-tveit-chicago-evanston-north-shore-realtor


Selling an Evanston Condo: What to Do Before You List
Selling a condo in Evanston is not quite the same as selling a single-family home. Buyers are evaluating not only your unit, but also the building, the association, the monthly assessments, the reserves, the condition of the common areas, and any upcoming projects or special assessments.
That means the preparation starts before the photographer arrives.
Read full article here: https://www.willtveit.com/selling-an-evanston-condo


North Shore vs. Chicago: Choosing a Condo
If you are looking for a condo north of downtown Chicago, there is a good chance your search will cross the city limits. A condo in Evanston, Wilmette, Winnetka or Highland Park may compete with one in Edgewater, Rogers Park, Uptown, Lakeview or Lincoln Park. Deciding between them is not always easy.
The North Shore has several distinct communities with access to the lake and commuter trains into Chicago. The North Side has a wide variety of neighborhoods and condo buildings within the city. Neither one is automatically better. It comes down to how you live, what you want included in your monthly costs and which tradeoffs you are willing to make.
Here are some of the most important factors to consider when comparing a North Shore condo with one on Chicago’s North Side.
Read the full article here: https://www.willtveit.com/north-shore-vs-chicago-condos


Evanston Condo Assessments: What Do HOA Fees Cover?
When comparing Evanston condos, buyers often focus on the monthly assessment: Is it high? Is it low? How does it compare with another building?
Those are reasonable questions, but the dollar amount alone does not tell the full story. One building’s assessment may include heat, water, parking and professional management, while another building’s lower assessment may cover only basic common-area expenses.
The better question is: What does the assessment cover, and what financial condition is the condominium association in?
Having owned a downtown Evanston condo since 2003, I have seen firsthand how widely services, amenities and operating costs can vary. Understanding those differences can help buyers make more meaningful comparisons.
Read the full article here: https://www.willtveit.com/evanston-condo-assessments-what-do-hoa-fees-cover


First-Time Home Buyer’s Guide to Chicago and the North Shore
Buying a condo involves more than evaluating the unit itself. You are also buying into a condominium association—and taking on a share of its financial condition, rules, maintenance responsibilities and future expenses.
A beautifully renovated condo can still be a risky purchase if the association has inadequate reserves, deferred maintenance, pending litigation or a large special assessment on the horizon. Conversely, an older building with well-maintained common elements and responsible financial planning may be an excellent investment.
That is why reviewing the condominium association’s documents is such an important part of buying a condo in Evanston.
Read full article here: https://www.willtveit.com/buying-a-condo-in-evanston-hoa-documents-reserves-special-assessments-and-red


First-Time Home Buyer’s Guide to Chicago and the North Shore

Friday, September 25, 2026
Condo Special Assessments: What Buyers and Sellers Need to Know
Special assessments can make condo buyers nervous, but they aren’t automatically a red flag.
What matters is why the assessment was necessary, how it’s being funded, the association’s financial condition, and what expenses may be coming next.
In my latest article, I look at what buyers should investigate, what sellers should know before listing, who may be responsible for an assessment when a condo is sold, and how special assessments can affect financing.
If you own—or are considering buying or selling—a condo in Chicago, Evanston, or the North Shore, it’s worth understanding how special assessments work.
Read the full article:
Condo Special Assessments: What Buyers and Sellers Need to Know


Friday, January 17, 2025

Thursday, April 11, 2024

Navigating the process of moving can be a daunting task, especially when faced with the unfortunate reality of dealing with unethical moving companies. It's crucial to safeguard yourselves against fraudsters who seek to exploit unsuspecting consumers. As your trusted realtor, I'm here to provide you with essential advice on how to protect yourself from falling victim to these scams.
Protecting Yourself Against Unethical Moving Companies:
Written Contracts:
- Ensure all agreements are in writing.
- Contracts should clearly detail services and costs.
- Seek clarification for any vague terms.
Beware of Dishonest Intermediaries:
- Verify legitimacy through research.
- Check history, reviews, and insurance coverage.
- Insist on face-to-face meetings for accurate quotes.
Watch Out for Hidden Fees:
- Gas, assembly/disassembly, bulky items, etc.
- Ensure all fees are clearly outlined in the contract.
- Avoid companies with unclear pricing structures.
If It Seems Too Good to Be True, It Probably Is:
- Trust your instincts.
- Prioritize transparency over enticing offers.
- Stay informed and vigilant throughout the process.
Stay Informed and Vigilant:
- Research moving companies thoroughly.
- Trust but verify all claims and promises.
- Prioritize transparency and clear communication.
Your Trusted Realtor is Here to Help:
- Count on your realtor for guidance.
- Empower yourself with knowledge.
- Ensure a smooth and hassle-free relocation experience.
By following these bullet points, you can safeguard yourself against fraudulent moving companies and ensure a successful relocation process.
For questions about your move, or to list your home or find a new one, don't hesitate to get in touch with me first!
Will Tveit | MBA-Broker-Realtor
Dream Town Real Estate: North Shore Chicago - Evanston
909 Davis Street, Suite 500
Evanston, IL 60201
will@dreamtown.com | willtveit.com
Mobile: 312.498.8348
Search for Homes with Zenlist! https://zenlist.com/a/will.tveit

Wednesday, February 12, 2020
Condo vs. Co-op: What's the difference?
Condo vs. Co-op: What’s the difference?
Will Tveit | MBA - Broker Associate - Realtor, Dream Town Realty

Condo vs. Co-op: What’s the difference?
In searching for an apartment, you might find some described as “condos” or “condominiums” and others as “coops” or “cooperatives.”
While it is true that many (but not all) coop apartments are located in classically designed pre-War buildings, the term “co-op” does not describe the style of the building but rather the ownership terms of the apartments.
With a condominium (or condo), you are buying a physical apartment (as defined by legal description) as well as a share in the common elements of the building. A condo association, led by a board of directors, manages the building’s exterior and common elements, including landscaping, while the unit owners maintain the interiors of their individual apartments.
When you purchase in a co-operative (or co-op), you are technically not buying real estate. Instead, you are purchasing shares of stock in a legal entity (usually a corporation) that owns real estate. Your shares of stock entitle you to occupy a specific apartment, as defined in the Proprietary Lease you receive with your stock certificate. So in the end, you have the same thing (a place to live), but how you achieve this is a bit different.
History of Co-op Apartments
Some of the finest pre-War and Art Deco buildings in Chicago’s Gold Coast, Lincoln Park, Lakeview, and Hyde Park neighborhoods are coops. Coops predated condominiums as the earliest form of apartment ownership in Chicago.
In the beginning, coops were popular among Chicago’s leading families. Each building had admission requirements, much like private country clubs. Their criteria included financial capacity and social stature. Because they were corporations, coops were exempt from fair housing rules and were able to discriminate. Bank financing was not available; purchasers paid for their shares of stock in cash.
In the late 1980s, banks started getting more creative, offering opportunities for co-op purchasers to discretely obtain financing. However, as coop financing was not allowed, shares of stock could not be openly pledged as collateral. Thus, the earliest coop loans were unsecured lines of credit. As shareholders could not sell their apartments without first retrieving these certificates, they needed to remain on good terms with the bank.
By 1994, some co-op buildings had started to openly permit shareholders to pledge their stock as collateral and obtain financing. This shift in policy made sense, as home mortgage interest deductions were (and still are) a valuable write-off against income taxes. As co-ops began to allow financing, it was with carefully designed rules that included:
- Limits on the percentage of the purchase price (or appraised value for existing co-op owners) that could be financed.
- The requirement that the lender executes a “recognition agreement” acknowledging the co-op's rights, especially with respect to approving future sales.
Today, there are only a few co-ops left in Chicago that require purchasers to pay 100% cash. The rest allow purchasers to obtain loans for anywhere from 55% to 90% of their purchase price depending on the building. Another major shift is that co-ops can no longer reject a potential buyer for reasons other than their ability to afford the home. Consequently, the make-up of coop residents is more diverse than in the past.
Maintenance Fees and Real Estate Taxes
Buyers new to co-ops are often surprised by the fact that the monthly fees for co-ops are higher than for condos. However, this is usually because co-op fees include two additional areas of expense that condo owners pay separately.
In both condos and co-ops, fees are collected from homeowners/shareholders to pay for building maintenance and insurance. In both cases, residents carry separate insurance for the interior components of their apartments including everything from the walls in.
But two other expenses are not handled the same way:
Real Estate Taxes
Both condo and co-op owners pay real estate taxes. But how they receive and pay their bills varies.
- In condo buildings, each homeowner receives a tax bill directly from Cook County.
- In co-ops, shareholders do not receive individual real estate tax bills. Instead, Cook County issues a single tax bill to the corporation. Shareholders pay a proportional share of the total bill based on the number of shares of stock they own. In most coop buildings, real taxes are included in the monthly assessments, similar to the way some condo or single-family homeowners may pay their real estate taxes each month into an escrow along with their mortgage payments.
Real estate taxes paid for condos and co-ops are tax-deductible and qualify for both homeowner’s and senior citizen exemptions.
Capital Projects
In all buildings (condos and co-ops), capital improvements are needed from time to time. These projects vary depending on the age and condition of the building and may include the need for tuckpointing, a new roof, new elevators, upgrades to the building’s electrical service, replacement plumbing risers, a new boiler, or new windows. While most buildings are diligent about maintaining a reserve fund for capital projects, there can be a gap between reserve fund balances and capital requirements, resulting in the need to collect additional funds from homeowners.
The way that condos and co-ops customarily fund capital improvements can be another distinguishing feature.
- Condo buildings typically utilize “special assessments” to pay for capital improvements. They can be structured as a one-time payment or as a series of payments over months or even years.
- Co-ops, on the other hand, can pledge the building as collateral and obtain a mortgage (or line of credit) that can be used to pay for capital improvements over a longer period of time. In such a case, shareholders pay their pro-rata share of the building’s monthly mortgage payment along with their regular maintenance fees. Obtaining a loan to pay for capital projects can be viewed as preferential over a special assessment, as the cost of the improvement is less burdensome. Any interest shareholders pay on the coop’s mortgage is tax-deductible, just like interest on their home loans.
Board Approval / Admission Requirements
In condo buildings, homeowners have virtually no say in who moves into the building. Some condo associations (mostly older ones) have a provision in their by-laws that gives them the “right of first refusal.” This provision was designed to provide a back-stop to prevent someone from dumping their apartment at an excessively low price, injuring values in the building. However, the hurdles involved in exercising a right of first refusal (including the requirement that the association buys the unit from the seller at their price) make it nearly impossible.
In condo buildings, homeowners have virtually no say in who moves into the building. Some condo associations (mostly older ones) have a provision in their by-laws that gives them the “right of first refusal.” This provision was designed to provide a back-stop to prevent someone from dumping their apartment at an excessively low price, injuring values in the building. However, the hurdles involved in exercising a right of first refusal (including the requirement that the association buys the unit from the seller at their price) make it nearly impossible.
Still, under the right of first refusal provision, condo associations may request copies of sales contracts, applications and/or credit reports.
Co-ops have a more involved application process. The main reason that co-ops still “approve” buyers in this day and age is to confirm the buyers’ ability to afford their homes, including association fees, real estate taxes and potential future capital improvements. If someone buys a co-op and stops paying their monthly assessments, neighbors would be on the hook for more than just their maintenance fees.
Consequently, co-op purchasers are usually required to provide the following: an application, a detailed balance sheet, and several personal and professional letters of reference. Some co-ops also ask to see tax returns. After the coop board has received and reviewed the buyer’s application, an interview is scheduled, and then the buyer is officially approved.
Most coops discourage flipping or buying purely for investment. For that reason, rentals are rarely allowed except under extenuating circumstances, and then, only with board approval.
Financing
Condo associations do not get involved in how purchasers finance their apartment. That is between the lender and the buyer. As noted earlier, most coops do have restrictions in this area, primarily as it relates to the amount a coop purchaser can borrow as a percentage of their purchase price. Most coops now allow buyers to borrow around 75% of their purchase price, some more and some less. However, a few buildings including 209 E. Lake Shore Drive, 1500 N. Lake Shore Drive, and 2430 N. Lakeview still require buyers to pay for their entire purchase in cash.
The good news is that the portfolio of loan products available to coop borrowers is relatively diverse and competitive with condo financing options.
Conclusion
In the last few decades, buyers have shifted away from co-ops.
- A large number of new condominium buildings came online with amenities like private outdoor space and deeded, onsite garage parking--perks that are not often available in pre-War buildings.
- The sky was the limit on what banks would lend condo owners, so many took advantage of this. Some people obtained highly leveraged loans, borrowing more than their purchase price.
- Many felt the co-op application process invaded their privacy, and they wanted to avoid it altogether.
Ironically, as over-leveraged condo owners and investors in certain buildings have failed to meet their obligations resulting in a drop in home values building-wide, the benefits of buying in a coop are making a comeback. While the coop approval process, caps on financing, and restrictions against buying for investment do not guarantee financial immunity for shareholders, they are a good hedge.

Friday, February 22, 2019
Will Tveit - Real Estate | My Blog - Market Conditions | willtveit.com
|

Friday, November 30, 2018
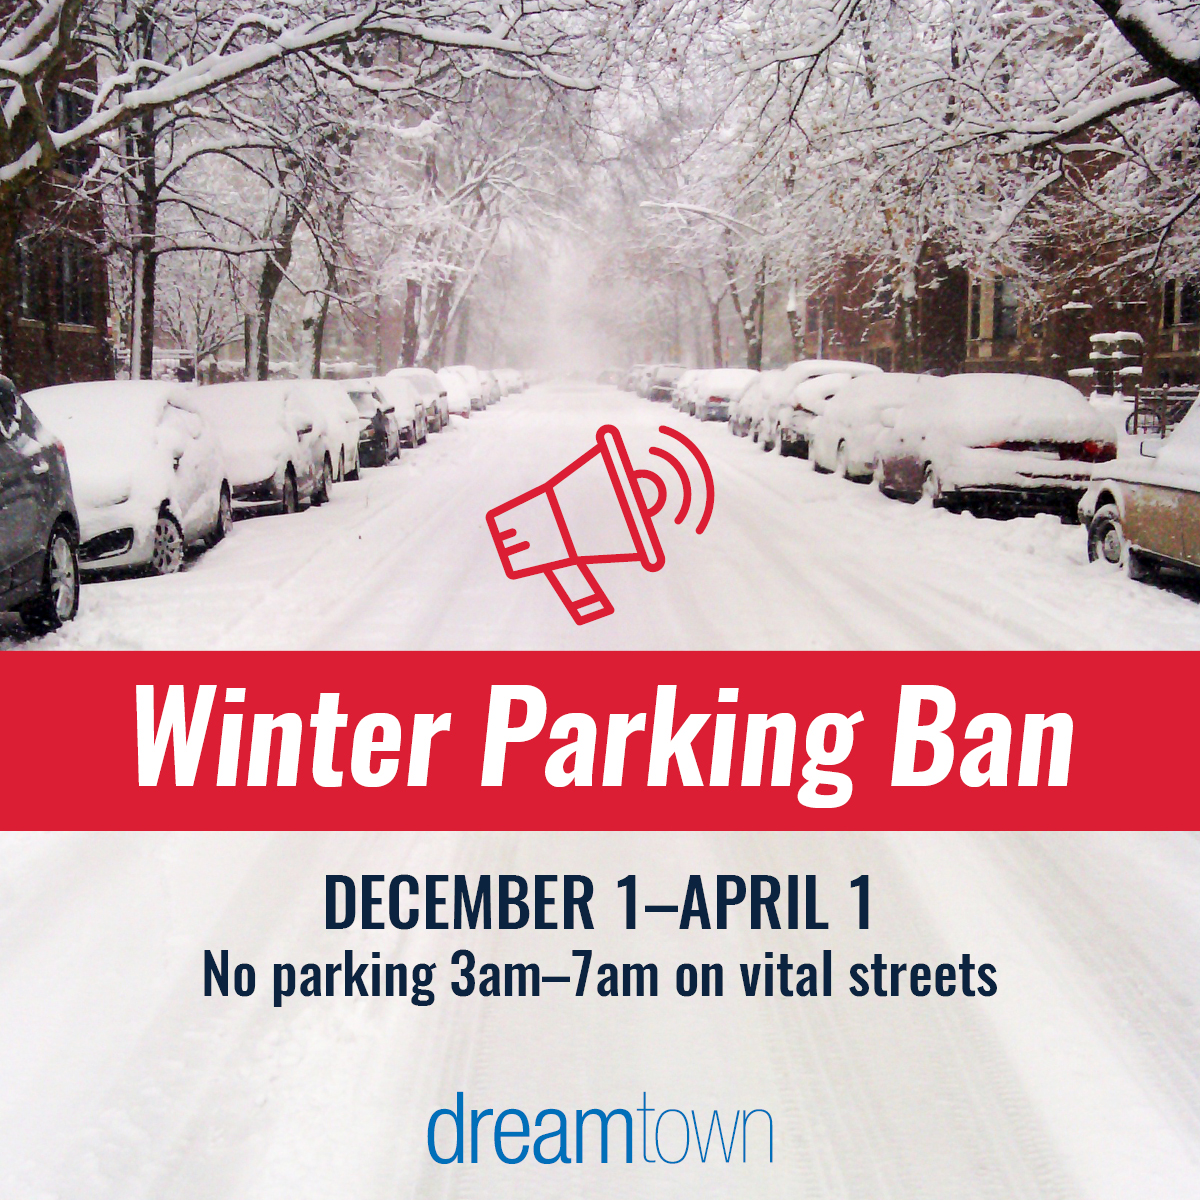
Chicago Winter Parking Ban - Public Service Announcement (PSA) willtveit - dreamtown

Lincoln Park: 1950 N Sedgwick | Lincoln Square: 4553 N Lincoln Ave | West Loop: 849 W Monroe
Northwest Chicago: 7280 W Devon | Evanston: 1567 Maple
Wednesday, June 6, 2018
Evanston Condo | Church Street Station | Will Tveit - Dream Town Realty
Church Street Station Condominiums | North Shore
1640 Maple Avenue, Unit 707, Evanston
2-bed | 2-bath | 2-garage spaces


Friday, June 1, 2018
Just Listed - Downtown Evanston - 2-bed 2-bath 2-pkg spaces | willtveit - dreamtown


 |
just listed
|
1640 MAPLE AVENUE #707
www.1640mapleevanston.com
| |
2 BEDROOM · 2 BATHROOM · EVANSTON
| |
 |   |
| SEE MORE PHOTOS & INFORMATION ABOUT ALL LISTINGS | |
2-BEDROOM 🏠 2-BATHROOM
EVANSTON
Bright and beautiful corner unit condo with fantastic city views. Large living room overlooks downtown Evanston, Lake Michigan and Chicago's skyline. Kitchen features maple cabinets and stainless steel appliances, granite countertops and separate eating area. Berber carpeting throughout living areas and bedrooms, in-unit w/d, master bedroom en-suite with large professionally organized walk-in closet, 6-panel doors, private balcony and storage and 2 garage spaces, all included within a luxurious full-amenity building that includes a fitness room, indoor pool, and party room. More info at: www.1640mapleevanston.com
|  Broker | Realtor 312.498.8348 will@dreamtown.com http://willtveit.com http://1640mapleevanston.com |
© 2018 Dream Town Realty Inc. All information subject to errors, omissions, prior sale, or withdrawal without notice ⌂
Unsubscribe | |
Subscribe to:
Posts (Atom)